Contents
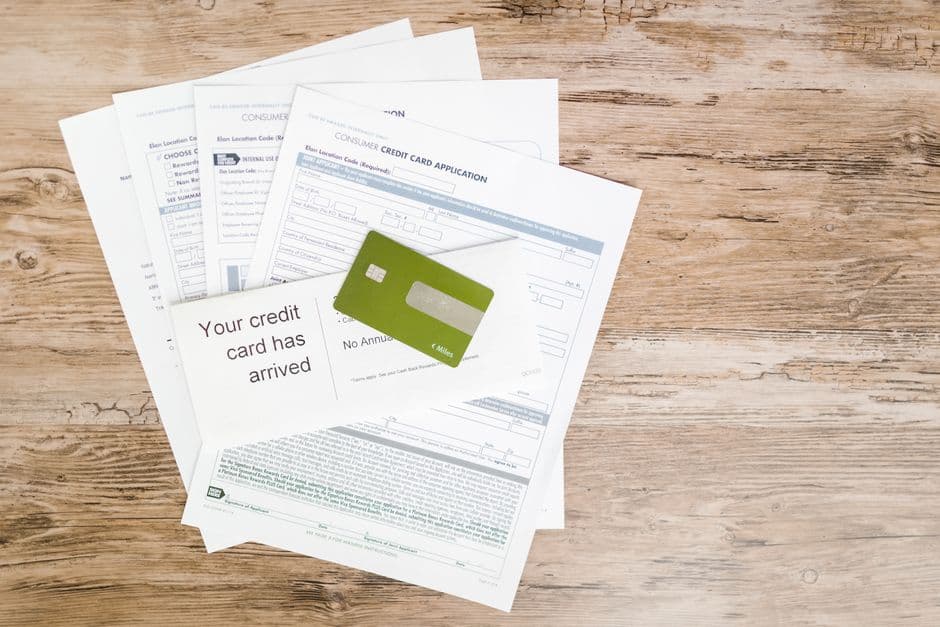
Understanding business credit card requirements helps you choose the right card and prepare a complete application. Each issuer sets its own approval standards. However, most lenders review similar information about your business, income, credit history, and intended use.
You do not always need a large company or established revenue. In fact, many cards accept freelancers, contractors, and sole proprietors. Therefore, the best approach combines accurate information, realistic expectations, and careful comparison.
Business Credit Card Requirements for Basic Eligibility
Most applicants must show a legitimate business activity. That activity can include consulting, online sales, freelance work, rental income, or professional services. Therefore, you may qualify even without employees or a formal corporation.
Issuers typically request your legal business name, business address, industry, and years in operation. They may also ask for your business structure, such as a sole proprietorship, partnership, or corporation. Always provide consistent information across your application.
Additionally, many applications request an estimate of annual business revenue. Use a reasonable figure based on current records. Do not include personal income as business revenue unless the application clearly permits that information.
Business Credit Card Requirements for Personal Information
Small-business card applications often require the owner’s personal details. You may need to provide your name, address, date of birth, Social Security number, and annual personal income. Issuers use this information to assess creditworthiness.
Your personal credit score can matter substantially, especially when your business has limited credit history. However, scoring models and approval standards vary by issuer. Therefore, review the card’s stated credit profile before applying.
Many business cards also require a personal guarantee. With a guarantee, you agree to repay eligible balances if the business cannot pay. Read the account agreement carefully, because business and personal liability can differ by product.
UpCardsCredit card comparatorPick 2 cards and see, line by line, what changes between them.Use it →How Personal Credit Affects Approval
A strong payment history can support your application. Conversely, recent late payments, high balances, or multiple new accounts may create concerns. Before applying, check your credit reports for errors.
You can request free credit reports through AnnualCreditReport.com, the official source authorized by federal law. Correct inaccurate information before submitting a new application.
Moreover, avoid applying for several cards within a short period. Multiple hard inquiries may affect your credit profile. Instead, compare eligibility guidelines first and select one suitable option.
Documents That Support Business Credit Card Requirements
Issuers may not request documents from every applicant. Still, you should keep useful records available. These records can help you answer questions or respond to a verification request.
- Business registration documents, when applicable
- An Employer Identification Number, or EIN
- Recent business bank statements
- Invoices, contracts, or sales records
- Tax returns or other income documentation
- A valid government-issued identification document
Sole proprietors may apply under their own legal names. They may also use a registered trade name, depending on local rules and issuer instructions. Therefore, confirm which name belongs on each application field.
An EIN can identify a business for tax and banking purposes. However, an EIN does not guarantee approval. Some sole proprietors can apply with a Social Security number instead.
Business Credit Card Requirements and Revenue Questions
Revenue questions often confuse new business owners. Issuers usually want an honest estimate of income generated by the business. They may also ask about the date the business began operating.
If your business has no revenue yet, answer accurately. Some products may accept applicants with projected revenue, while others may require existing income. Never inflate figures to improve your approval chances.
Furthermore, separate business revenue from personal income when the application requests both figures. Personal income can include wages or other reliable sources. Business revenue describes money earned through business activity.
Choosing the Right Card Before You Apply
First, identify your main spending categories. For example, you might prioritize advertising, travel, office supplies, fuel, or employee purchases. Then, compare rewards, annual fees, interest rates, and redemption rules.
Next, review employee card controls and expense management tools. These features can simplify bookkeeping and reduce unauthorized spending. However, they may not matter for a one-person business.
You can also learn more here about comparing financial products and organizing business finances. A careful comparison can reduce unnecessary applications and fees.
Business Credit Card Requirements After You Apply
The issuer may approve, decline, or request additional information. A verification request does not automatically mean rejection. Respond promptly and provide clear, accurate documents.
Review the approved account details before activating the card. Check the credit limit, annual fee, introductory terms, and payment due date. Also, confirm whether the account reports activity to commercial credit bureaus.
Finally, establish a payment system from the beginning. Pay on time, monitor balances, and keep business purchases separate from personal spending. These habits support cleaner records and more disciplined cash flow.
If the issuer declines your application, read the adverse action notice. It should explain important reasons for the decision. You can address those factors before considering another application.
Common Mistakes With Business Credit Card Requirements
Applicants often confuse business eligibility with corporate size. A business does not necessarily need employees, a storefront, or years of operating history. Still, it must represent genuine commercial activity.
Another mistake involves entering inconsistent information. Differences between your application, tax records, and business registration can trigger questions. Therefore, gather your records before you begin.
Finally, applicants sometimes focus only on rewards. Interest charges, annual fees, and payment terms also affect the account’s value. Choose a card that matches your spending habits and repayment plan.
Frequently Asked Questions
Do I need an EIN to meet business credit card requirements?
Not always. Many sole proprietors can apply with a Social Security number. However, corporations and other registered entities may use an EIN.
Can a new business qualify for a business credit card?
Yes, some issuers accept new businesses. They may rely more heavily on the owner’s personal credit and income. Always provide honest revenue information.
Does applying for a business credit card affect personal credit?
The issuer may perform a personal credit inquiry during the application. In addition, some issuers report account activity to consumer credit bureaus. Check the card agreement for details.
What should I do after a business card application denial?
Review the denial notice and identify the stated reasons. Then, check your credit reports, improve relevant factors, and wait before submitting another application.
Conclusion
Business credit card requirements usually include business details, personal information, income estimates, and credit review. However, exact standards vary by issuer and product.
Prepare accurate records, compare card terms, and choose an account that fits your business. Moreover, use the card responsibly after approval. Timely payments and organized records can support healthier financial management.