Contents
Learning how to lower monthly payments can create breathing room without abandoning your long-term financial goals. Start by reviewing every bill, interest rate, balance, and due date.
Moreover, avoid quick fixes that simply extend debt. A lower payment may increase your total cost. Therefore, compare the monthly relief with the full repayment amount before choosing a strategy.
How to Lower Monthly Payments With a Clear Budget
First, list your housing, transportation, insurance, utilities, debt, and subscription costs. Then, separate essential bills from flexible spending. This process reveals where your money goes each month.
Next, review your last three bank statements. Look for recurring charges, convenience fees, and irregular expenses. However, do not cut essential insurance or minimum debt payments without a safer replacement.
Finally, set a payment target that fits your reliable income. Include a small emergency buffer. Otherwise, one unexpected expense could force you to use expensive credit again.
How to Lower Monthly Payments by Reducing Interest
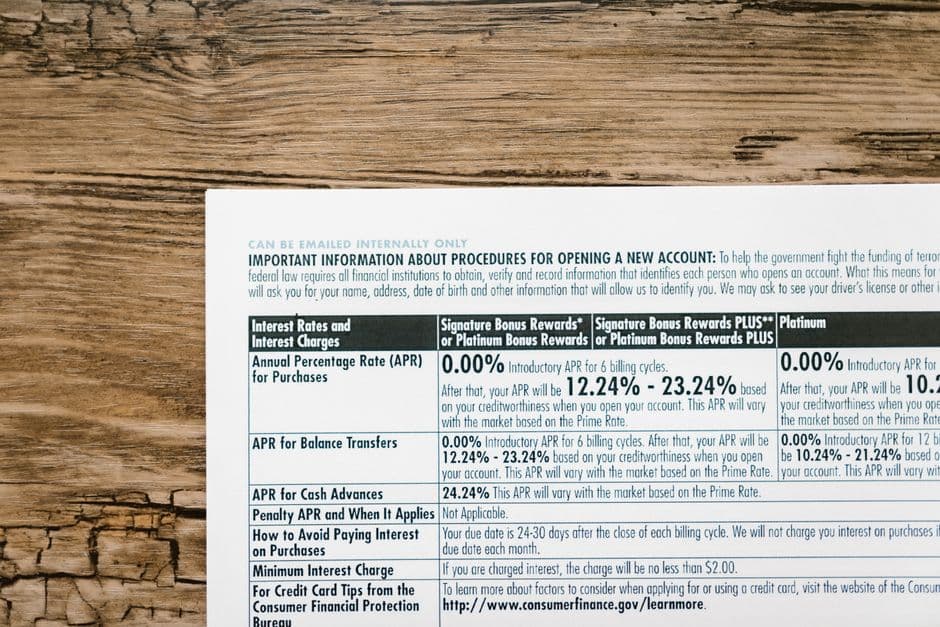
Interest often drives high monthly payments, especially on credit cards and personal loans. Therefore, contact your lender and ask about a lower rate, hardship plan, or temporary payment arrangement.
Prepare before you call. Gather your account history, income details, payment record, and proposed monthly amount. Moreover, explain the change clearly and request written terms before accepting anything.
For broader consumer guidance, review information from the Consumer Financial Protection Bureau. It explains common lending options and potential risks.
UpCardsCredit card comparatorPick 2 cards and see, line by line, what changes between them.Use it →How to Lower Monthly Payments Through Refinancing
Refinancing replaces an existing loan with new terms. A lower interest rate can reduce your payment, especially when your credit profile has improved. However, approval depends on income, credit history, debt, and collateral.
Compare more than the advertised rate. Check origination fees, closing costs, penalties, loan length, and the total interest. A longer term may lower your payment but increase your total cost.
Before applying, check your credit reports for errors. Also, avoid submitting many applications at once. Multiple hard inquiries can complicate your profile and reduce your available options.
How to Lower Monthly Payments With Debt Priorities
Choose a repayment method that matches your behavior. The avalanche method targets the highest interest rate first. In contrast, the snowball method targets the smallest balance first.
Both methods require minimum payments on every account. Then, direct extra money toward one priority balance. Once that balance disappears, transfer its payment to the next account.
You can also explore nonprofit credit counseling. A counselor may review your budget and discuss a debt management plan. Still, verify fees, services, and possible effects on your accounts.
How to Lower Monthly Payments Without Creating New Problems
Do not use a cash advance to cover ordinary bills. Likewise, avoid payday loans and high-fee financing. These products can provide short-term relief while increasing your long-term burden.
Consider practical changes that reduce recurring costs. You might compare insurance quotes, remove unused subscriptions, negotiate internet service, or use public transportation. Small reductions can support larger debt payments.
Keep records of every agreement. Save emails, confirmation numbers, payment dates, and account statements. Furthermore, review your plan monthly and adjust it when your income or expenses change.
When a Lower Payment Requires Professional Help
Seek qualified advice when you face collection calls, possible foreclosure, repossession, or overwhelming medical debt. An attorney, housing counselor, or nonprofit counselor may explain options that fit your situation.
Be cautious with companies that guarantee instant debt relief. No legitimate provider can promise approval or erase every obligation. Therefore, research complaints, fees, contracts, and cancellation policies first.
You can learn more here about building a sustainable payment strategy. Choose a plan that improves cash flow without hiding the real cost.
Frequently Asked Questions
What is the fastest way to lower monthly payments?
Start by contacting each lender. Ask about hardship programs, lower rates, fee waivers, or revised due dates. However, compare the new total cost before agreeing.
Does refinancing always reduce the total cost?
No. Refinancing may lower the monthly payment while extending the loan term. Check the interest rate, fees, repayment period, and total amount paid.
Can budgeting lower my payments without a new loan?
Budgeting may reduce your overall monthly pressure by removing unnecessary expenses. It does not change a lender’s required payment, but it can free money for debt repayment.
Conclusion
Learning how to lower monthly payments starts with accurate numbers and realistic priorities. Review your budget, negotiate with lenders, and compare refinancing offers carefully.
Moreover, protect your future cash flow. Avoid high-cost shortcuts, keep written records, and seek qualified help when debt becomes unmanageable. A lower payment matters most when it supports lasting financial stability.